Few things test an investor like watching a portfolio lose 20, 30, or 40 percent of its value in a matter of weeks. The headlines turn apocalyptic, your account balance keeps shrinking, and every instinct tells you to do something, usually to sell everything and make the pain stop.
That instinct is understandable, and it is also one of the most expensive mistakes an investor can make. Market crashes are painful, but they are also a normal, recurring part of investing. How you behave during one often matters more than which stocks you own going into it. This article covers why crashes feel so threatening, what history says about them, and what you can actually do to protect and even grow your wealth when markets fall.
Why a Crash Feels So Dangerous- Human brains are not built for investing. Behavioral economists have shown that losses hurt roughly twice as much as equivalent gains feel good, a pattern called loss aversion. When your portfolio drops, your brain registers it as a threat, much like physical danger, and triggers the urge to flee.
Several other biases pile on. Recency bias makes us assume whatever just happened will keep happening, so a falling market feels like it will fall forever. Herd behavior makes selling feel safe when everyone around you is doing it. And the constant stream of alarming news creates a sense that this time is different.
Recognizing these tendencies is the first step toward managing them. Panic is not a character flaw. It is a predictable response, which means you can plan for it in advance.
First, Check Your Foundation – Before deciding anything about your investments, look at your overall financial position. A crash is most dangerous to people who are forced to sell at the bottom.
Do you have an emergency fund? Three to six months of expenses in cash or a savings account means a job loss or surprise bill won’t force you to liquidate investments at depressed prices. If your emergency fund is thin, rebuilding it is a higher priority than buying the dip.
When will you need this money? Money you need within the next few years, such as a house down payment or tuition, should not be in stocks to begin with. Money you won’t touch for 10, 20, or 30 years has time to recover. If a crash has revealed that you took more risk than you can tolerate, that is useful information, but making big changes in the middle of a panic is rarely wise.
Do you have high-interest debt? Paying off credit card debt at 20 percent or more is a guaranteed return that beats most investments. Don’t sacrifice that for speculation.
What to Do During a Crash
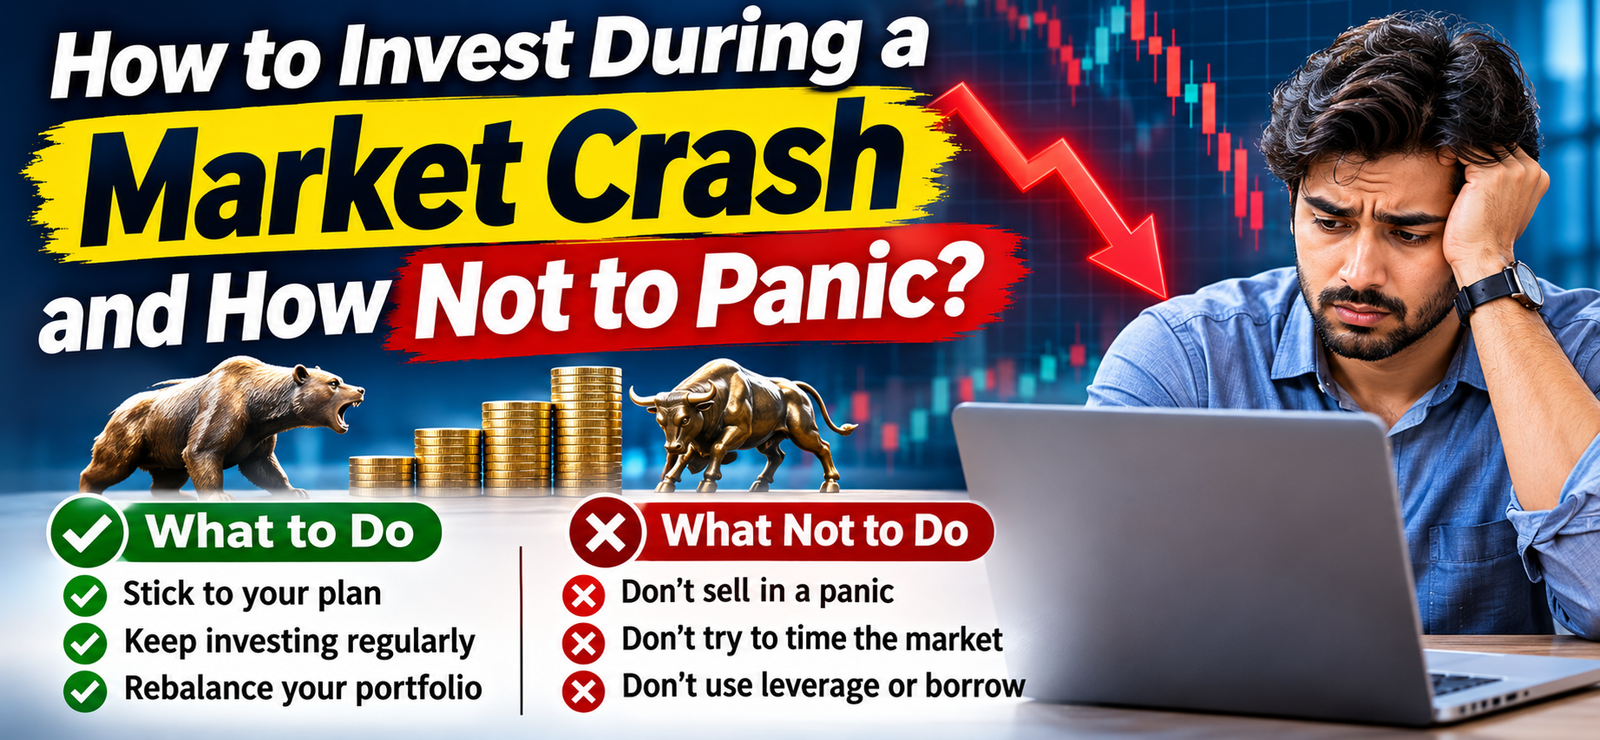
1. Stick to Your Plan- If you have a written investment plan, now is the time to follow it. A good plan is built for exactly this scenario. If you don’t have one, the best thing you can do is avoid making sweeping changes while emotions are running high. For most people, doing nothing is a legitimate and often optimal strategy.
2. Keep Investing Regularly- If you contribute monthly to a retirement account or invest through a systematic plan, keep going. This approach, known as dollar-cost averaging, means your fixed contribution buys more shares when prices are low and fewer when they are high. Falling markets are when this discipline pays off, because you are accumulating assets at a discount. Investors who stopped contributing during past crashes often missed the cheapest purchase prices of their lives.
3. Rebalance Your Portfolio- Suppose your target is 70 percent stocks and 30 percent bonds. After a crash, stocks might drop to 55 percent of your portfolio. Rebalancing means selling some bonds, which have usually held up better, and buying stocks to return to your target. It forces you to buy low in a disciplined, rule-based way, without needing to predict the bottom.
4. Consider Tax-Loss Harvesting- If you hold investments in a taxable account, a downturn creates an opportunity to sell positions at a loss and use those losses to offset capital gains or, within limits, other income. You can then reinvest in a similar but not identical asset to maintain your market exposure. Tax rules vary by country and have specific restrictions, such as wash-sale rules in the US, so check the details or consult a tax professional.
5. Favor Quality and Diversification- Crashes tend to expose weak businesses: companies with heavy debt, thin profits, or fragile business models. If you are adding money, broad, low-cost index funds spread your risk across hundreds or thousands of companies, so you don’t have to guess which will survive. If you pick individual stocks, focus on companies with strong balance sheets, durable earnings, and competitive advantages.
6. Put New Cash to Work Gradually- If you have a lump sum to invest, trying to time the exact bottom is a losing game. Nobody reliably calls it, and the bottom is obvious only in hindsight. Instead, consider spreading purchases over several weeks or months. This reduces the risk of investing everything right before another leg down, and it reduces the regret of waiting too long.
What Not to Do
Don’t sell in a panic. Selling after steep losses turns temporary declines into permanent ones. If you must reduce risk, do it based on a rational reassessment of your goals, not on fear.
Don’t try to time the market. Selling now and planning to buy back “when things calm down” requires being right twice, on the exit and the re-entry. Most investors who try end up buying back at higher prices than they sold.
Don’t use leverage or borrow to invest. Margin loans can force you to sell at the worst moment if prices keep falling. A crash is not the time to add that kind of risk.
Don’t chase hot tips or exotic assets. Crashes bring out confident voices promising safe havens or guaranteed rebounds, and scammers thrive when people are scared. Be skeptical of anything promising outsized returns with little risk.
Don’t check your portfolio constantly. Watching your balance several times a day does nothing but amplify anxiety. Looking at it monthly or quarterly is plenty for most long-term investors.
Don’t ignore your own risk tolerance. If a 30 percent drop kept you awake at night, your portfolio may be too aggressive for you. Once the dust settles, adjust it to a level you can actually live with, so you can stay invested through the next downturn.
A Practical Anti-Panic Toolkit- Staying calm is easier with a few concrete habits.
Write your plan down. Put your goals, time horizon, and target allocation on paper while you are calm. When markets fall, reread it before touching anything.
Add a cooling-off period. Commit to waiting 48 to 72 hours before making any major investment decision. Most urges to sell fade with time.
Limit your news diet. Financial media profits from attention, and alarming headlines draw more of it than calm ones. Reduce your exposure.
Zoom out. Look at a 20 or 30 year chart of the market. The crash you are living through will look very different as a small dip on a long upward line, though remember that this is no guarantee for the future.
Talk to someone. A trusted friend, a fee-only financial advisor, or a community of long-term investors can offer perspective when your own judgment is clouded.
Focus on what you control. You can’t control the market, but you can control your savings rate, your costs, your diversification, and your behavior.
The Opportunity Hidden in the Fear- It may sound strange, but long-term investors have reason to welcome falling prices, at least in principle. If you are still working and adding to your portfolio, lower prices mean you are buying future earnings more cheaply. The legendary investor Warren Buffett has long advised being “fearful when others are greedy, and greedy when others are fearful.” That is easy to say and hard to do, but it captures a real truth: the best long-term returns are often earned by those who keep investing when it feels the most uncomfortable. None of this makes crashes painless. Watching your wealth shrink is genuinely stressful, and there are no guarantees about how long a recovery will take. The goal is not to feel nothing. It is to feel the fear and still act sensibly.
Conclusion- Market crashes are inevitable, but financial ruin from them is not. The investors who come through best tend to share a few traits: they hold an emergency fund so they never become forced sellers, they diversify, they keep contributing regularly, they rebalance with discipline, and above all they resist the urge to make dramatic moves based on fear. Build your plan before the storm, write it down, and follow it when the storm arrives. The next crash will come, as every one before it has. When it does, your preparation and your temperament, more than any clever prediction, will determine how well you fare.